LOMA in Pinellas: How to Get Your Home Out of a FEMA Flood Zone (2026 Homeowner Guide)
This guide walks through the LOMA process end-to-end for Pinellas County homeowners. If your home was recently elevated or sits on natural high ground and you want the mandatory flood insurance lifted, our flood zone contractor team coordinates the surveyor, engineer, and compliance filing. Not sure whether LOMA, elevation, or a deep remodel is the right path? Try the Flood-Zone Decision Calculator.
The Short Version
A Letter of Map Amendment (LOMA) is a free FEMA determination that officially removes your home from a Special Flood Hazard Area on the Flood Insurance Rate Map. If your property sits on natural high ground above the Base Flood Elevation, or you've elevated the structure above BFE, filing a LOMA can drop mandatory flood insurance premiums from $5,000-$6,000 per year in AE to $500-$800 per year in X. You'll need a licensed Florida surveyor to shoot an elevation certificate ($500-$1,200), then FEMA typically returns a determination in 60-90 days.
A LOMA can be one of the most valuable pieces of paper a Pinellas homeowner ever files. The federal application itself is free. The full cost — surveyor plus documentation — usually lands under $1,200. And when it lands, it can flip your flood insurance bill from “bigger than the tax bill” to “bigger than a Netflix subscription.” This guide walks through exactly what a LOMA is, when it's possible, the financial math, and the 8-step process from surveyor call to policy re-rate.
What Is a Letter of Map Amendment (LOMA)?
A Letter of Map Amendment is a FEMA-issued official document that amends the Flood Insurance Rate Map (FIRM) for a specific property. The amendment removes the home — or a designated portion of it — from the Special Flood Hazard Area (SFHA), which is the umbrella term for AE, VE, AO, and AH zones.
The mechanical trigger for the amendment is proof that the property actually sits above the Base Flood Elevation (BFE), even though the mapped FIRM panel currently classifies it as below. FIRM panels are drawn at scale across huge geographies. Individual lots — especially lots on natural mounds, higher parcels, or homes that have been physically elevated — can sit above BFE while the map still shows them inside the SFHA.
The result of a successful LOMA is that federal law no longer requires flood insurance for a federally-backed mortgage on the property. Your mortgage servicer must drop the mandatory-coverage flag. Your insurance carrier will re-rate the policy at the reclassified zone (typically X), or you can cancel it entirely. On a $5,000-$6,000 annual AE-zone premium, that's $4,000-$5,000 per year back into the homeowner's pocket, every year, for the life of the LOMA.
One important note: a LOMA does not lower your actual flood risk. It amends the map for insurance-rating purposes. Any Pinellas homeowner who lived through Hurricane Idalia or Helene knows that even X-zone properties can flood in a large enough storm. Most homeowners keep voluntary X-zone flood coverage after a successful LOMA — but voluntary X-rate premiums run a small fraction of mandatory AE.
When Is a LOMA Possible?
Not every AE-zone home is a LOMA candidate. FEMA needs a demonstrable elevation reason to amend the map for your parcel. Four scenarios come up regularly in Pinellas:
- Home sits on natural ground higher than BFE. Some Pinellas neighborhoods contain pocket ridges and higher lots that the FIRM panel didn't resolve. If a surveyor can show the lowest floor and lowest adjacent grade sit above BFE on native soil, LOMA is straightforward.
- Lot is on a mound or higher parcel that wasn't captured on the FIRM. Waterfront neighborhoods often have small elevated pockets where the modeled floodplain expanded past the actual high ground. Shore Acres has documented cases of higher interior parcels; Old Northeast has Coffee Pot Bayou-adjacent mounds; Snell Isle has interior high spots.
- Fill (added earth) that raised the home above BFE. When compacted fill has been placed and engineered to raise a lot before construction, FEMA can amend the map based on the finished grade. This path uses form MT-1 rather than the simpler MT-EZ.
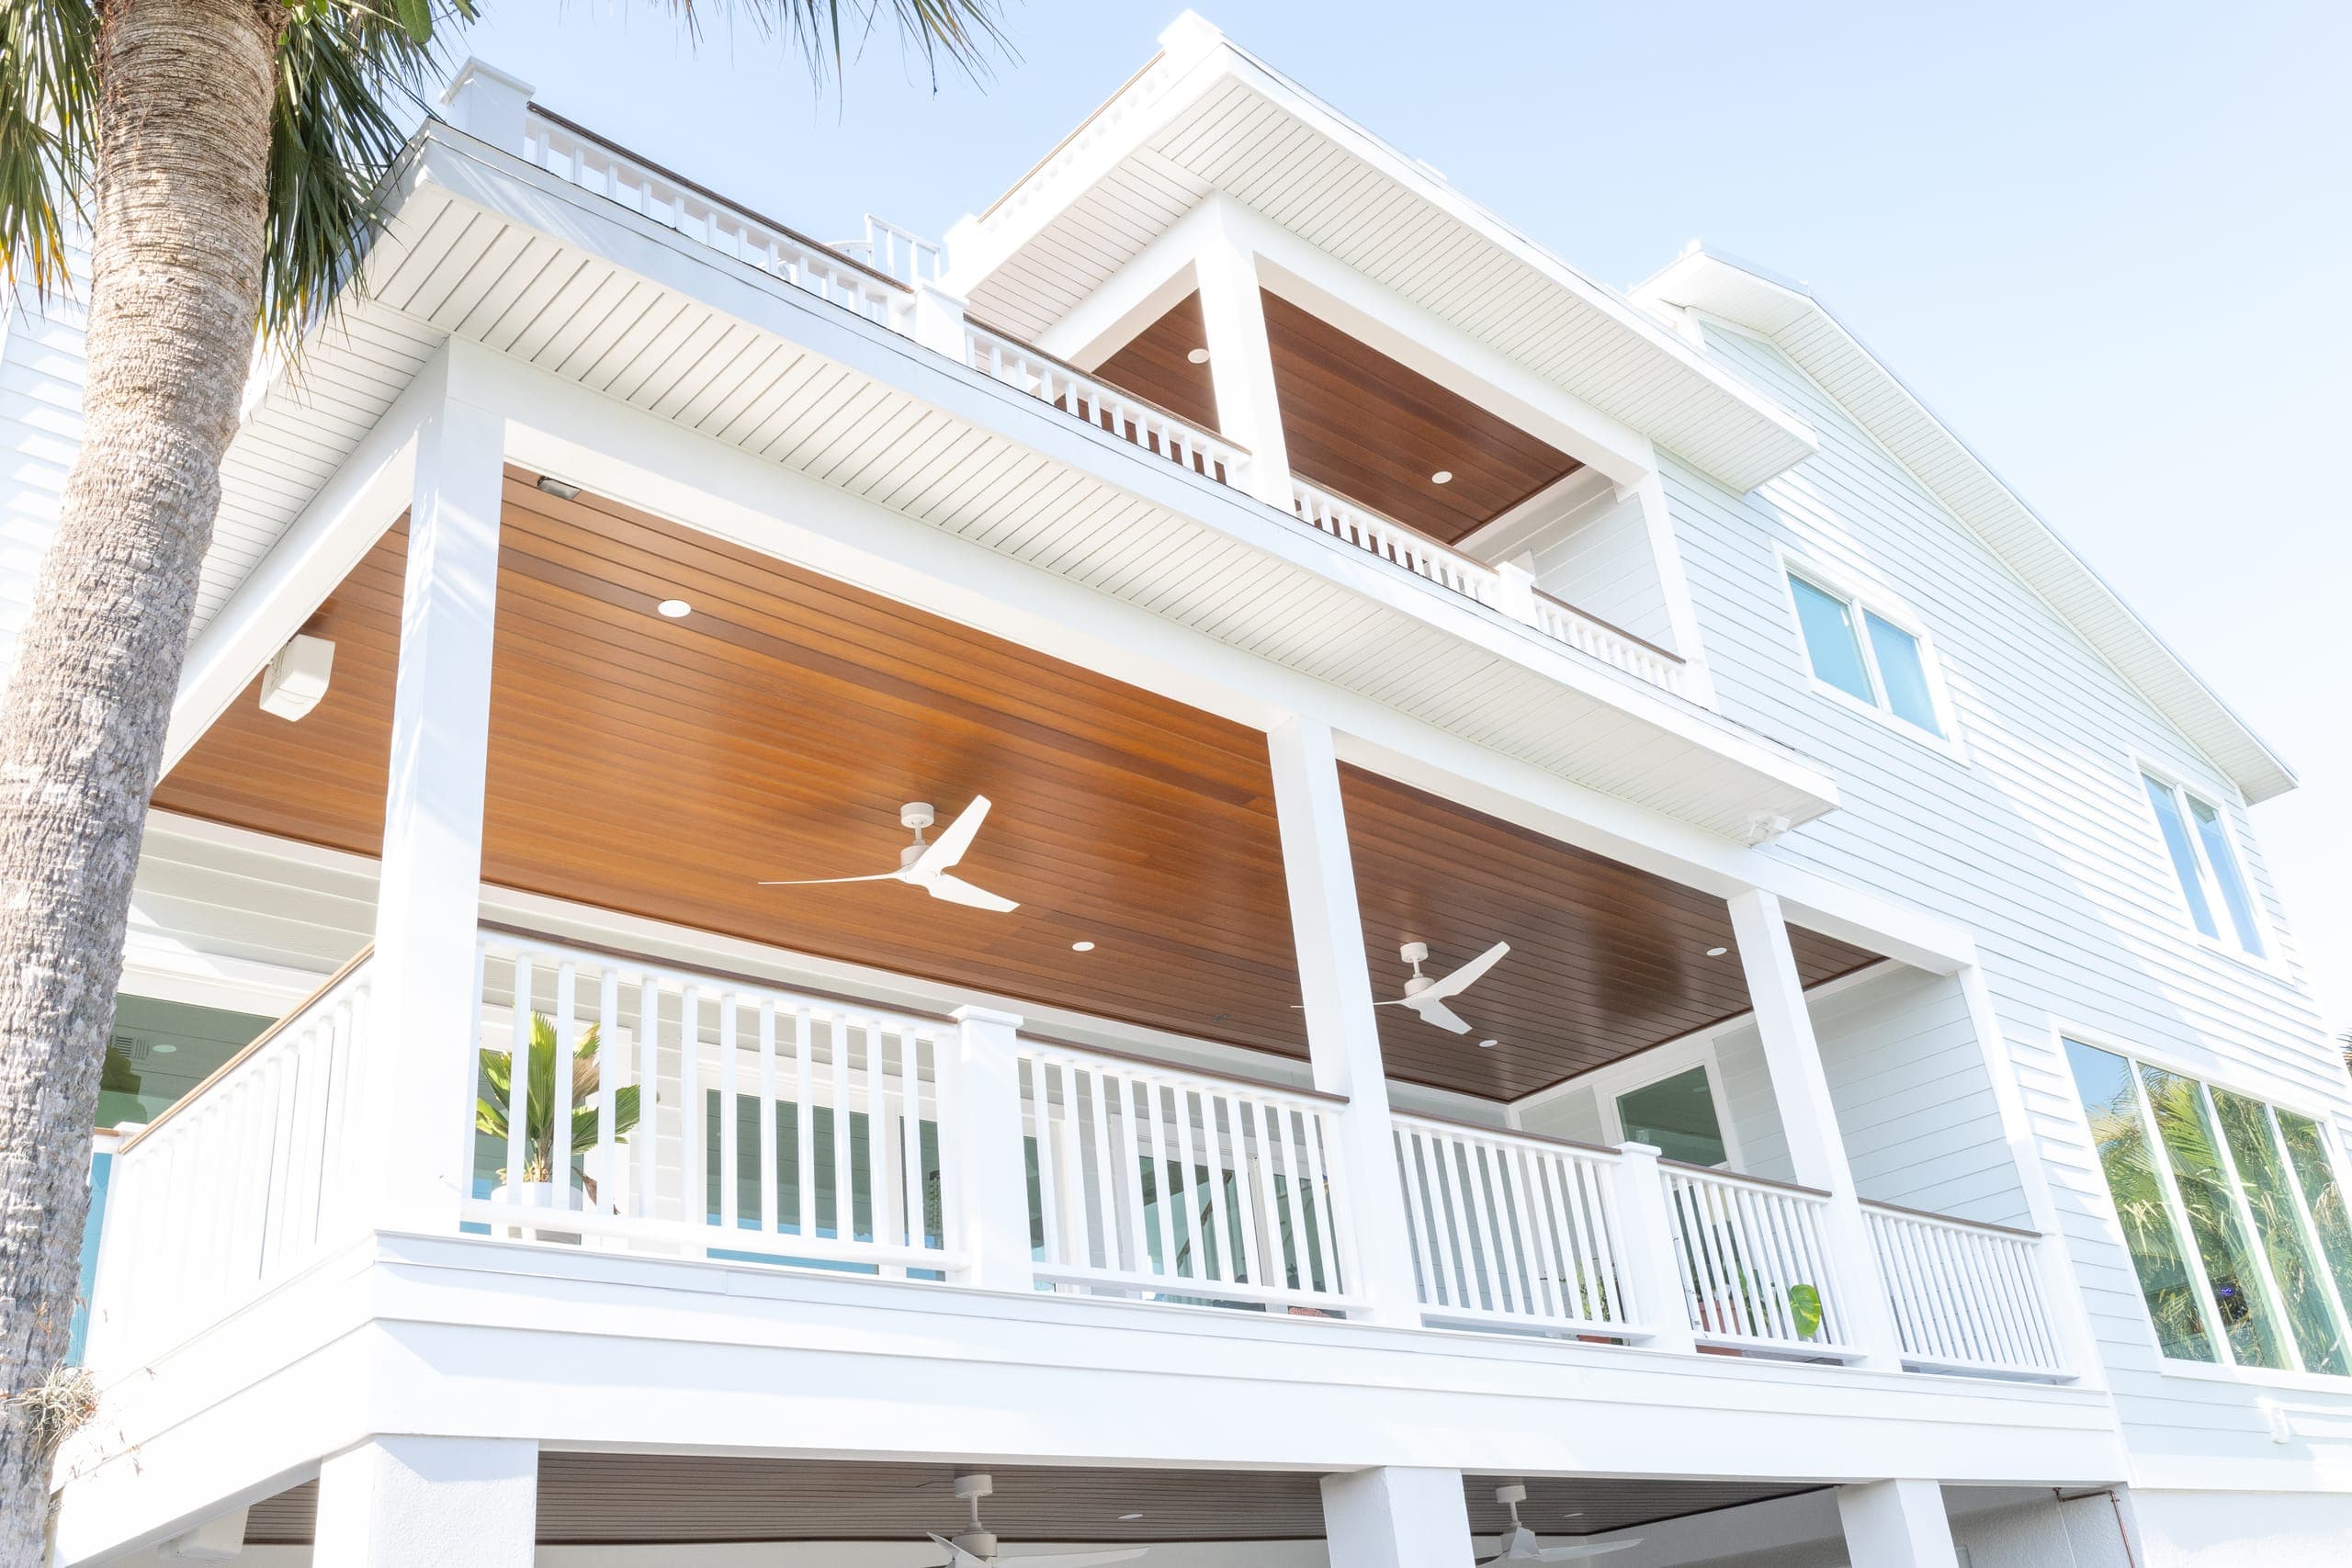
- Structural elevation completed after the FIRM date. This is the strongest case in modern Pinellas: a home elevated through a full house-elevation project ends up with a certified finished floor well above BFE. Post-elevation LOMAs are nearly automatic when the elevation certificate is clean. See our house-elevation cost guide and elevated house plans for flood zones for the construction side.
If none of those four apply — your home sits at or below BFE on natural grade with no fill and no elevation project — LOMA is not the right tool. The path forward is usually elevation, either through the Elevate Florida program or a private elevation project, followed by LOMA.
LOMA vs LOMR vs eLOMA — Which One Applies to Your Property?
FEMA publishes three related tools. They're easy to confuse and pick incorrectly, which is one of the most common reasons a filing gets denied.
- LOMA (Letter of Map Amendment) — Single-property amendment based on natural elevation or post-elevation certified structure. No fill involved. Uses FEMA form MT-EZ. This is what most Pinellas homeowners actually need.
- LOMR (Letter of Map Revision) — Revises the FIRM map itself for a larger area or for fill-based changes. Used when engineered fill has been placed to raise a property, or when a large floodplain revision affects multiple parcels. Requires more extensive engineering documentation. Uses form MT-1.
- eLOMA — The expedited electronic online process. Only licensed surveyors, engineers, and architects can file eLOMA on your behalf. When your surveyor confirms your case is a clean natural-grade or post-elevation LOMA, ask if eLOMA applies — determinations can return in as little as one day rather than the 60-90 day standard-LOMA window.
The Financial Math — Why LOMA Matters in Pinellas
The reason LOMA rises to the top of the flood-zone toolkit is the insurance math. Pinellas AE-zone premiums under Risk Rating 2.0 have climbed sharply since 2021, especially post-Ian, post-Idalia, and post-Helene.
Representative AE-to-X example on a Pinellas single-family home:
- Pre-LOMA (AE zone): $5,000-$6,000 per year mandatory NFIP premium on a $500K-$700K coastal home. Many higher-value or lower-elevation homes run $7,000-$10,000+.
- Post-LOMA (X zone, voluntary coverage): $500-$800 per year for the same coverage limits at the reclassified X-zone rate.
- Annual savings: $4,000-$5,000+ per year, every year, for as long as you own the home.
- LOMA total cost: $500-$1,200 (surveyor + elevation certificate). FEMA filing is free.
- Break-even: 3-6 months after the LOMA is issued.
Where LOMA comes up most in Pinellas: Shore Acres higher lots (interior parcels above the typical waterfront BFE), Old Northeast homes near Coffee Pot Bayou on natural high ground, Snell Isle interior elevations, Tierra Verde lots away from the seawall, and any post-elevation home in Venetian Isles, Bahama Shores, or the barrier islands. If you're curious what zone your parcel currently sits in and how a LOMA might play, our AE vs VE vs X zone guide walks the map side and our full Pinellas flood-zone guide has the neighborhood breakdown.
How to File a LOMA — 8-Step Homeowner Walkthrough
Step 1: Get an elevation certificate from a Florida-licensed surveyor
Hire a licensed FL surveyor to shoot the lowest floor elevation (or lowest adjacent grade for a LOMA based on natural high ground), the surrounding grade, and record it on FEMA's Elevation Certificate form. Cost typically runs $500 to $1,200 in Pinellas.
Step 2: Confirm home and structural finished floor elevation is above BFE
The surveyor will compare your measured elevation against the Base Flood Elevation on the current FIRM panel for your property. If the lowest floor (or lowest adjacent grade for natural-ground LOMAs) sits above BFE, you have a viable LOMA case.
Step 3: Prepare the LOMA application (FEMA form MT-EZ or MT-1)
MT-EZ is the simpler form for straightforward single-lot residential LOMAs on natural ground. MT-1 covers more complex cases including fill-based cases, structures on mounds, and portions-out-as-shown filings. Your surveyor or engineer will typically prepare the form as part of their scope.
Step 4: Submit to FEMA with the surveyor's elevation certificate
Filing is free. Submit online through FEMA MIP (Mapping Information Platform) or by mail. Licensed surveyors and engineers can use the eLOMA electronic path for expedited review. Include the stamped elevation certificate, current FIRM panel reference, and a property survey.
Step 5: FEMA review (typically 60-90 days)
FEMA reviews the elevation certificate against the current FIRM data, verifies the property boundaries, and issues a determination letter. If additional data is needed, expect a request-for-information (RFI) letter that adds 30-60 days to the timeline.
Step 6: Receive LOMA determination letter
FEMA issues either a LOMA (property removed from SFHA), a LOMA-Out As Shown for partial removal, or a denial letter. Keep this letter on file — you will provide it to every future mortgage lender, insurance carrier, and buyer of the property.
Step 7: Provide the LOMA to your mortgage lender and flood insurance carrier
Send certified copies to your mortgage servicer to lift the mandatory flood insurance requirement and to your flood insurance carrier to re-rate or cancel the policy. Lenders will still recommend voluntary flood coverage on Pinellas parcels — the LOMA lifts the mandate, not the underlying flood risk.
Step 8: Get the flood-insurance requirement lifted or policy re-rated
Once the lender confirms the LOMA and drops the mandatory-coverage flag, your mandatory NFIP premium ends. Most homeowners keep voluntary coverage at the reclassified X-zone rate — typically $500 to $800 per year in Pinellas versus the $5,000-$6,000 AE-zone rate — because X zones still flood during major events. Even voluntary X-zone coverage is dramatically cheaper than mandatory AE.
Documents You'll Need
- Current elevation certificate from a licensed Florida surveyor, stamped and dated within the last 12 months. FEMA rejects older certificates when grade or structure has changed.
- Property survey showing lot boundaries, structure footprint, and any attached improvements (garage, decks, additions).
- Photos of the home and surrounding grade — the FEMA reviewer uses these to sanity-check the elevation certificate against reality. Include the front elevation, at least one side, and any below-BFE features (attached garage, crawlspace vents, breakaway walls if VE).
- FIRM panel showing current classification — pull the current effective FIRM panel from the FEMA Flood Map Service Center (msc.fema.gov) or the Pinellas County Property Appraiser's FEMA/WLM letter tool (pcpao.gov). The application must reference the specific panel number and effective date.
- Legal description of the property — from the deed or the property appraiser record.
Common LOMA Denial Reasons
FEMA denies more LOMAs than most homeowners expect. The four denial reasons that account for the majority of no-answers in Pinellas:
- Home actually at or below BFE. Surveyor error or an assumption that the front-yard grade was representative of the finished floor. Every LOMA case turns on the specific measured elevation of the lowest floor (or lowest adjacent grade for natural-ground filings), not the average lot elevation.
- Wrong FIRM panel referenced. Pinellas has been through several FIRM updates. Applications that reference a superseded panel get rejected — always pull the current effective panel.
- Incomplete documentation. Missing the property survey, missing photos, missing legal description, or an elevation certificate that omits the surveyor's stamp all trigger a request-for-information letter and add 30-60 days.
- Attached garage below BFE. Common on elevated homes. FEMA may issue a LOMA-Out As Shown (LOMA-OAS) instead of a full LOMA — the main structure is amended out of the SFHA, but the attached garage keeps its flood-zone designation. Some lenders accept LOMA-OAS to lift the mandatory coverage on the primary residence; others require the entire footprint out.
What Revolution Helps With
Revolution Contractors is a Pinellas County general contractor with $20M+ of coastal flood-zone work completed since 2016, licensed in Florida as CRC1331628. We're not surveyors and we don't file LOMAs directly for homeowners — the elevation certificate has to come from a licensed FL surveyor by law. What we do on the LOMA side:
- Surveyor and engineer coordination. We work with the surveyors and structural engineers on our Pinellas flood-zone projects every week. If your project needs an elevation certificate, we can point you toward the surveyors who work quickly and stamp cleanly.
- Elevation verification during renovation projects. When a substantial-improvement remodel is in play and the numbers are close to BFE, we build in mid-project verification checks so the finished floor lands where the plans said it would.
- Compliance documentation for post-elevation LOMA. Paired with our home elevation scope — when we elevate a home, we deliver the finished project with the elevation certificate lined up so the LOMA can be filed the same week the certificate of occupancy hits.
- Pinellas floodplain administrator coordination. Every Pinellas municipality — St. Pete, Gulfport, Pinellas Park, Treasure Island, St. Pete Beach — has a designated floodplain administrator. We know the ones handling active permits and can shortcut the back-and-forth that homeowners get lost in.
If you're combining a LOMA plan with a substantial-improvement remodel, our FEMA 50% rule guide explains the trigger that forces full elevation. If a storm has already damaged your home and the LOMA question comes up on the recovery side, see our FEMA 50% rule help page and flood damage recovery.
FAQ
How much does a LOMA cost?
The FEMA application itself is free — there is no filing fee for a residential LOMA. The real cost is the licensed Florida surveyor who prepares your elevation certificate, which typically runs $500 to $1,200 in Pinellas County depending on lot complexity and whether crawlspace or piling measurements are needed. If FEMA denies the initial LOMA and you appeal with additional survey data, add another $300 to $700. Compared with a $5,000-$6,000 annual flood insurance premium in an AE zone, the survey pays for itself in the first few months post-approval.
How long does the LOMA process take?
FEMA's published review window is 60 days from a complete application. In practice, most Pinellas LOMA determinations return in 45 to 90 days if the elevation certificate and FIRM panel references are clean. eLOMA — the expedited online path used by licensed surveyors and engineers — can return a determination in as little as one day for straightforward natural-grade cases, but only qualified surveyors and engineers can file eLOMA on your behalf.
Can I file a LOMA without a licensed surveyor?
Technically yes — a homeowner can file MT-EZ or MT-1 directly with FEMA. In practice, FEMA requires elevation data certified by a licensed surveyor, engineer, or architect for the application to succeed. Every LOMA determination we've seen in Pinellas required a stamped elevation certificate. Filing without one is almost guaranteed to get a denial letter. Save the time and go to a licensed FL surveyor first.
Does a LOMA lower my property taxes?
No. A LOMA amends the FEMA Flood Insurance Rate Map for insurance-rating purposes only. It doesn't change the Pinellas County Property Appraiser's just-value assessment, which is what drives your property tax bill. The tax savings a LOMA creates are indirect — buyers pay more for a house that isn't in an SFHA, which raises resale value, but the current-year tax bill is unchanged.
What if my home is only partially above BFE?
FEMA can issue what's called a LOMA-Out As Shown (LOMA-OAS) — the map is amended for the portion of the structure that's above BFE, but attached garages, decks, or lower additions below BFE keep the flood-zone designation for those specific features. Some lenders and carriers will still lift the mandatory flood insurance requirement based on the primary structure LOMA-OAS; others require the entire footprint to be out. Talk to your lender and carrier before betting on partial removal.
Can I combine LOMA with an elevation project?
Yes — this is one of the strongest financial plays in Pinellas coastal remodeling. Elevate the home to or above BFE + freeboard through a full house-elevation project, get an as-built elevation certificate at project close, then file the LOMA immediately. The post-elevation LOMA is nearly automatic when the elevation certificate is clean, and it locks in the reduced flood insurance premium going forward. We coordinate the surveyor, engineer, and compliance paperwork on elevation projects so the LOMA filing is ready to submit the day the certificate of occupancy hits.
Elevated your Pinellas home and ready to file LOMA? We coordinate the survey and compliance.
Revolution Contractors handles Pinellas flood-zone construction end-to-end — elevation projects, compliance documentation, and surveyor coordination so the LOMA filing lands the day the certificate of occupancy does. Licensed CRC1331628, since 2016, 20+ W-2 carpenters on payroll.